Most retirement decisions can be revisited. You can adjust your withdrawal rate. You can change investment allocations. You can claim Social Security earlier or later if circumstances change.
Pension elections are different. Once you elect a payout form — single life, joint and survivor, lump sum, or partial — the choice is generally permanent. There is no do-over. The decision affects every monthly check for the rest of your life and, often, your surviving spouse's life as well.
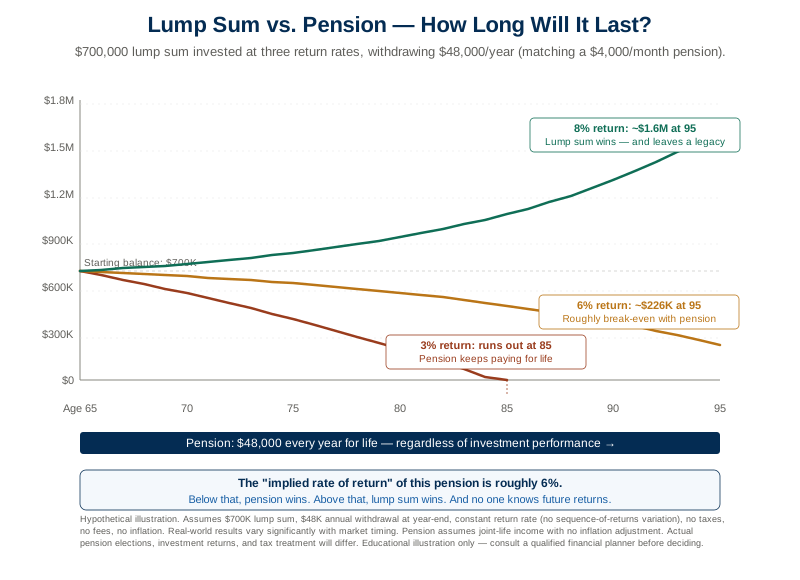
For workers with substantial pensions (corporate, federal, state, or union), the pension is frequently their largest single financial asset — sometimes worth $500,000 to $2 million or more in present value when calculated as a stream of lifetime income. A decision of that size deserves more than the 30-day window most plans give you to sign and return the paperwork.
This page won't tell you what to choose. It will help you understand the trade-offs so you can decide — with the right professionals at the table.